India Crypto Tax Rules 2026: What’s New vs What’s Unchanged
Are India Crypto Tax Laws Now More Strict: 148A Notices, Penalty & TDS
The Wild West days of trading digital coins in India are officially over. If you have ever bought or sold Bitcoin, Ethereum, or any other token, the Income Tax Department is now watching closely. With new AI tools and strict laws, the government is making sure every trade is tracked and taxed.
Why You Must Understand India Crypto Tax Rules Now
Recently, the India crypto tax office sent out over 44,000 notices (called 148A notices) to people who traded cryptocurrencies in the 2021-22 year. Using smart AI engines, they found nearly ₹889 crore in money that was not reported. These notices are not bills yet, but they are a "show-cause" warning.
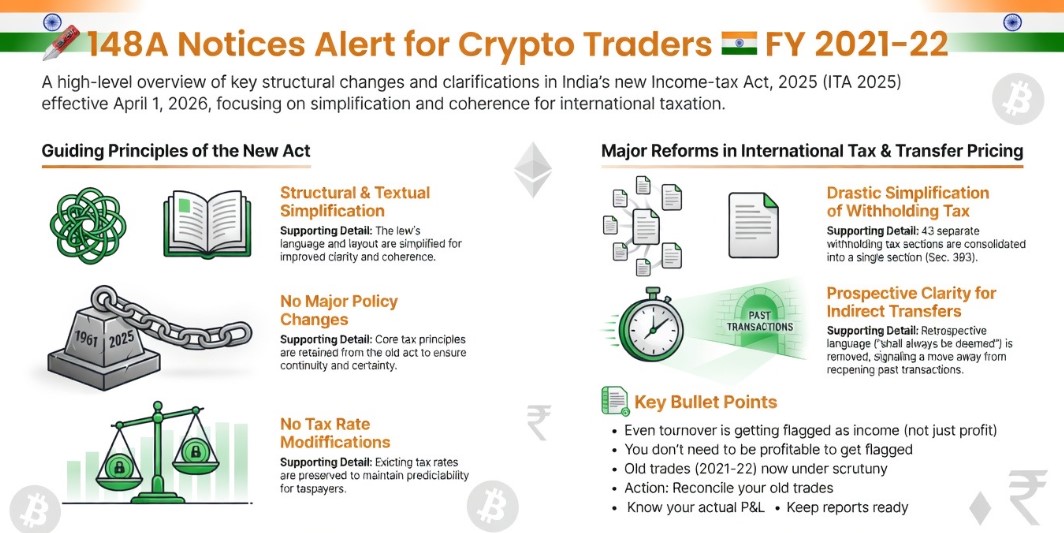
Source: X Official (@cryptopatel)
The government is now matching your PAN card, bank accounts, and exchange data. Many traders are seeing "inflated income" on these notices because the system sometimes looks at the total trading volume instead of just your profit. This makes it vital to keep clear records and talk to a professional.
New India Crypto Tax Regulations Starting April 2026
From April 1, 2026, the rules are getting even tighter. All Indian crypto exchanges must report every single trade to the tax-office. If they miss a filing, they face a ₹200 daily penalty. If the data is wrong, they could be fined ₹50,000.
Here is what the India Crypto Tax system looks like right now:
30% Flat-Tax: You must pay 30% on all profits (unchanged in Budget 2026).
No Loss Offset: If you lose money on one coin, you cannot use that loss to lower the duty on a coin where you made a profit.
1% TDS: A 1% levy is deducted at the source for every trade.
GST: You still pay GST on platform fees.
The Global Future: CARF and April 2027
If you think trading on foreign websites will keep your money hidden, think again. In April 2027, Indian regulators will join the Crypto-Asset Reporting Framework (CARF). This is a global deal where countries automatically share cryptocurrency data. This means the Indian government will soon know about your offshore wallets and international trades too.
How to Stay Safe and Compliant
Despite the high taxes, India crypto adoption is booming. With over 119 million users, the country is a world leader in cryptocurrency. To stay out of trouble while the Indian cryptocurrency laws evolve, follow these simple steps:
Check Your AIS: Look at your Annual Information Statement (AIS) and match it with your exchange records.
File Your Returns: If you missed filing taxes for past years, do it now.
Keep Records: Save every buy and sell receipt.
Talk to a Pro: Consult a CA who understands India crypto tax news and codes before replying to any government notice.
The era of hidden digital asset is gone. While the 2026 budget did not give us a tax-cut, it made the rules very clear. Staying honest with your taxes is the only way to keep trading safely in the country’s growing digital market.
Note: The article is for informational purposes only; It does not constitute any claims or advice.
Also read: