FATF Crypto Travel Rule Explained: What It Means and How It Works
FATF Crypto Travel Rule Explained: What It Means and How It Works
Money moving between two bank accounts usually carries the sender's name and details along with it.
Crypto never worked that way until the FATF Crypto Travel Rule stepped in and changed the picture for exchanges and other crypto businesses worldwide, tightening up crypto AML compliance in the process.
FATF stands for the Financial Action Task Force, an international body set up to fight money laundering and the financing of terrorism.
What Does FATF Actually Do?
FATF itself doesn't run exchanges or write national laws directly. It sets global standards that member countries build into their own regulations instead.
A broader look at crypto regulation by country shows how unevenly those standards actually get applied once they reach national governments.
FATF's own publication on virtual assets explains that it pushes countries to apply anti-money laundering rules to virtual asset service providers, called VASPs, the same way those rules already apply to banks.
A VASP covers exchanges, custodians, and other businesses that hold or move crypto on behalf of customers. India's approach fits this pattern too, and its own crypto regulation framework builds directly on that same FATF foundation, just with local tax and reporting rules layered on top.
How the FATF Crypto Travel Rule Works in Practice
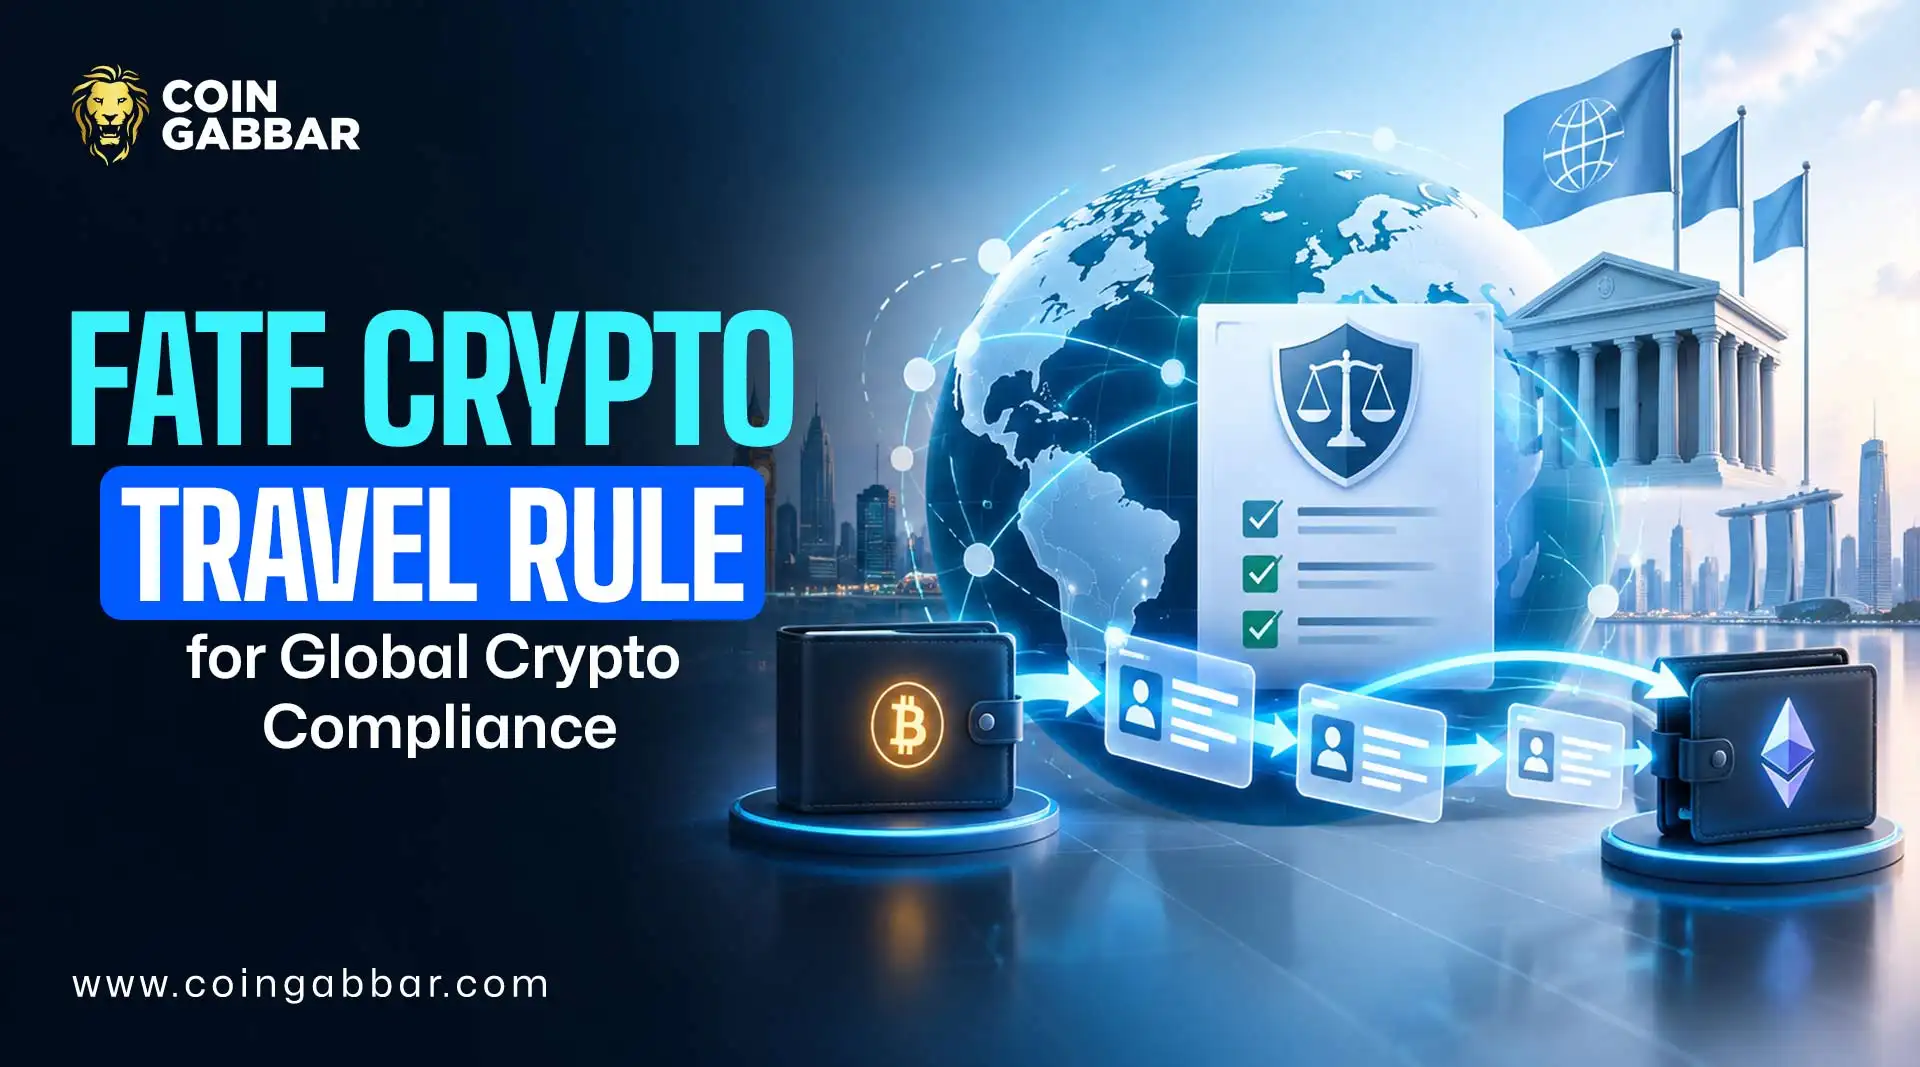
The rule requires a VASP sending crypto to another VASP to share specific details about who sent the funds and who's receiving them.
That usually includes names, wallet or account identifiers, and sometimes an address or ID number tacked on for good measure.
This information moves alongside the transaction, though not on the blockchain itself. It travels through separate, secure messaging systems built specifically for this one purpose.
A few points matter here:
The rule applies once a transfer crosses a set threshold, which varies by country
Both the sending and receiving VASP carry obligations under the rule
Peer-to-peer transfers between two personal wallets generally sit outside its scope
In the United States, that threshold sits at $3,000 under guidance from the Financial Crimes Enforcement Network, which confirmed in 2019 that existing wire transfer rules apply directly to crypto transactions too.
Why FATF Extended This Rule to Crypto
Crypto transactions can cross borders in seconds, often without revealing who is actually behind them.
That speed, paired with a lack of attached identity, made crypto an attractive tool for money laundering, according to FATF's own guidance for virtual assets.
By requiring the same sender and receiver information already expected in traditional banking, FATF aimed to close that gap without banning the technology outright.
This same compliance mindset now reaches into other corners of the industry, including how crypto events handle regulation and participant screening.
How Widely Is the FATF Crypto Travel Rule Followed Today?
Adoption has grown steadily but unevenly. FATF's own 2026 targeted update reported that a large majority of surveyed jurisdictions had passed travel rule legislation, though enforcement still varies a great deal from country to country.
Some regions, like the European Union, apply the rule with no minimum threshold at all, meaning every transfer needs full sender and receiver details. Other countries set a specific amount before the requirement kicks in.
What This Means for VASPs and Crypto Users
For a VASP, compliance means building systems to collect, verify, and transmit customer information securely and to check that a receiving platform can actually handle that data properly.
Getting this wrong can mean regulatory penalties or blocked transactions.
For an everyday user, the practical effect is usually invisible. Sending crypto between two compliant exchanges works the same as before, just with identity details quietly passed along behind the scenes.
Basic wallet security habits still matter just as much, since the FATF Crypto Travel Rule protects against money laundering, not against phishing or a lost seed phrase.
What Does the Data Say About Global Compliance?
The stronger signal from recent FATF reporting is steady, if slow, progress. More jurisdictions pass legislation each year, and enforcement actions have started appearing in places that once lagged behind.
Recent coverage of crypto hacks and security incidents shows how much is still at stake when compliance gaps line up with weak security elsewhere in the system.
Key Risks Tied to the Travel Rule
A few risks are worth keeping in mind:
Thresholds and requirements differ from country to country, which can complicate cross-border transfers
Smaller VASPs often struggle to afford proper compliance systems
Sharing personal information across borders raises real data privacy concerns
Falling short of compliance can cost a business fines or even its operating license
Conclusion
The FATF Crypto Travel Rule brought crypto transfers a lot closer to how traditional banks already handle sender and receiver details. It doesn't ban or restrict crypto directly, but it does push exchanges and other VASPs to build real compliance systems around it. Adoption keeps spreading worldwide, though enforcement and consistency between countries still have a way to go.
Disclaimer
This article is for general information only and isn't legal or financial advice. Rules and enforcement around the FATF Crypto Travel Rule differ from country to country and keep shifting, so it's worth checking official sources directly for whatever's current.
Also read: