How Crypto Lending Platforms Work and What Are the Risks
Crypto Lending, Explained Without the Jargon
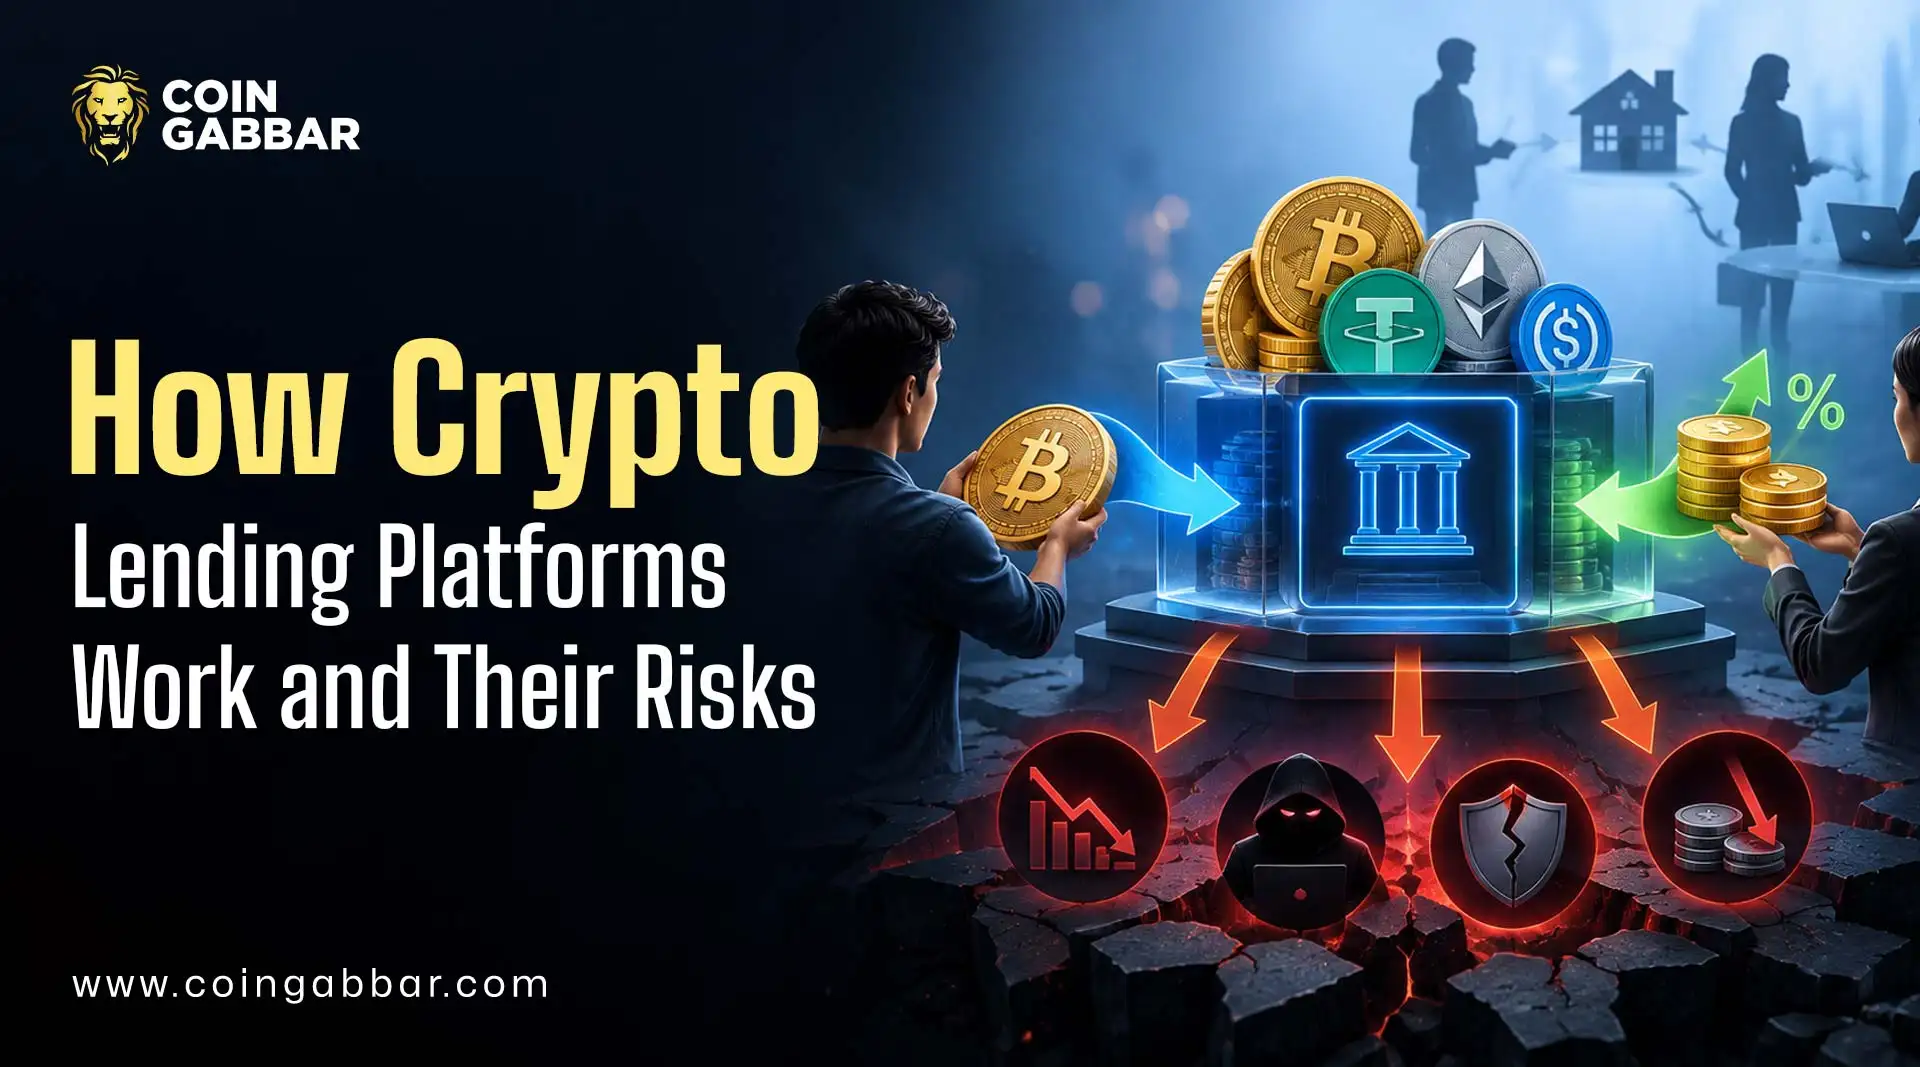
A crypto lending platform basically lets someone do one of two things: deposit their coins and earn interest or put up collateral and borrow against it. That's the short version of how crypto lending platforms work, though the details end up mattering a lot more than the pitch.
There's no bank teller checking a credit score here, and no branch to walk into if something goes sideways. It's smart contracts or centralized custodians running the whole show, and each setup carries its own kind of risk.
This guide walks through how the lending side actually works, what collateral and liquidation mean once money is actually on the line, and where the real risk sits for anyone thinking about depositing funds.
Beginners still getting their footing with exchanges and platforms in general might also want to glance at the best crypto exchange for beginners guide before diving into lending specifically.
How Do Crypto Lending Platforms Actually Work?
Most crypto lending comes down to one fairly simple idea: a depositor puts crypto into a pool, and a borrower takes a loan out of that same pool by putting up collateral worth more than what's borrowed. Understanding how crypto lending platforms work really starts with that one mechanic.
That's called overcollateralization, and it exists for a reason; there's no credit check here. The collateral itself backs the loan, not someone's financial history.
On decentralized platforms, smart contracts handle everything on their own. Deposits, interest, and even liquidations all happen through code, with no company signing off along the way.
According to Aave's own protocol documentation, collateral must stay above the borrowed amount at all times for this to function without anyone's credit ever being checked.
Centralized platforms work differently. A company holds the funds directly and runs the lending internally, closer to how a regular bank operates, just without the same regulatory backing behind it.
This is really where how crypto lending platforms work splits into two very different paths, depending on which model someone ends up using.
Readers still getting comfortable with how DeFi actually works might want to check the yield farming guide, since lending is really just one type of yield strategy.
For a look at how this plays out on a regulated centralized platform instead, the best regulated crypto exchange comparison covers that side.
What Happens When Someone Borrows Crypto?
Borrowing starts with collateral. Someone deposits an asset like ETH, and the protocol lets them take out a smaller loan in something else, often a stablecoin, against it.
How much depends on the collateral's value and whatever risk settings that protocol has set for that asset, one of the core mechanics behind how crypto lending platforms work.
Every open position gets tracked through what's usually called a health factor or collateral ratio. If the market value drops too far, the position gets liquidated on its own, or all of that collateral gets sold off to cover the debt before things go underwater. It protects the pool, sure, but it can also mean losing a chunk of collateral fast during a sharp price swing, sometimes within minutes.
According to MakerDAO's official liquidation documentation, once a position falls below its required collateralization level, the protocol automatically transfers the collateral into an auction and sells it off to cover the outstanding debt.
Anyone wanting to see how volatile collateral pricing actually gets handled might find the Chainlink and DeFi guide worth a look, since price accuracy is really what this whole mechanism depends on.
What Do Lenders Actually Earn?
Lenders put crypto into a pool and earn interest that borrowers pay, plus sometimes extra token rewards thrown in to pull in more liquidity.
Rates float with supply and demand; more borrowers push the rate up, and it drifts back down when a pool sits idle- something easier to size up once yields get compared against a platform like the best crypto exchange for USDT, since stablecoin pairs tend to sit right next to lending pools when it comes to where yield actually shows up.
A high advertised rate isn't free money. It usually means more risk sitting somewhere in that pool, whether that's a shakier collateral asset or an untested protocol.
According to Compound's official liquidation documentation, rates and risk are directly tied to how close a pool's borrowed positions sit to their liquidation thresholds, which is why a rate can look great one week and drop the next once that risk shifts.
Crypto Lending Models Compared
Model | How It Works | Custody | Main Risk |
Decentralized protocol | Smart contracts match lenders and borrowers on their own. | The non-custodial user keeps the wallet | Smart contract bugs, liquidation risk |
Centralized platform | A company manages deposits and lending internally. | The custodial platform holds the funds | Platform insolvency, mismanagement |
Peer-to-peer lending | Individual lenders and borrowers matched | Varies by platform | Counterparty and default risk |
The table makes the point simply: "crypto lending" isn't one single thing. Trusting code and trusting a company are two very different kinds of risk.
What Are the Real Risks of Crypto Lending?
A few risks show up again and again, no matter which platform someone picks:
Liquidation risk. A sharp drop in the collateral asset's price can trigger automatic selling, sometimes at a worse price than expected when things get volatile fast.
Smart contract risk. A bug in the code can wipe out funds, even on platforms that passed a smart contract audit. An audit lowers the odds of something going wrong; it doesn't erase them.
Platform insolvency. Centralized lenders that mismanaged funds or overextended their lending have gone under before, and depositors weren't always made whole afterward.
Interest rate volatility. Rates can swing fast depending on pool demand, so whatever rate shows up at deposit time isn't locked in for good.
Regulatory uncertainty. How these platforms get classified and regulated is still changing in a lot of places, and the rules can shift with little warning.
What Does the Data Say About Crypto Lending Platforms?
The stronger signal is that overcollateralization actually works. Automated liquidation has kept most major protocols solvent through several sharp downturns, and that track record is real.
The main concern is concentration risk. A handful of large protocols hold most of the value locked across DeFi lending, so a bug in one tends to ripple across the wider market instead of staying contained.
The biggest unknown is how regulators eventually treat these platforms, especially centralized ones offering interest accounts without the same protections as a bank. That's worth checking locally before committing real funds.
The Chainlink and DeFi guide covers how bad price data has triggered unfair liquidations before.
Conclusion
Crypto lending platforms work by matching depositors who want yield with borrowers putting up collateral, either through smart contracts or a company managing things centrally. The reward is interest on deposits. The risks are liquidation, smart contract failure, and, on centralized platforms, the company's own solvency.
Checking whether a platform is custodial or non-custodial, understanding how liquidation actually triggers, and never treating a high rate as risk-free are the practical steps before depositing anything.
Comparing lending against other yield strategies, like the Solana staking guide, is a reasonable way to see how risk differs across options.
Disclaimer
This article is for general information only and isn't financial advice. Crypto lending comes with real risk, including liquidation and the potential loss of funds, and a platform doing well in the past doesn't mean it'll keep doing well going forward.