What Is a Wash Trading Scandal in Crypto? A Simple Breakdown
What Is a Wash Trading Scandal in Crypto?
Every so often, a token's trading volume shoots up overnight with no real reason behind it. No big announcement, no partnership news, nothing. That is usually the first hint of a wash trading scandal, and once someone starts looking closer, the pattern tends to fall apart pretty fast.
Every wash trading scandal that comes to light adds one more reminder that headline numbers on an exchange are not automatically trustworthy just because they look impressive, whether that's on a small token or a platform ranked among the top crypto exchanges.
How a Wash Trading Scandal Actually Plays Out
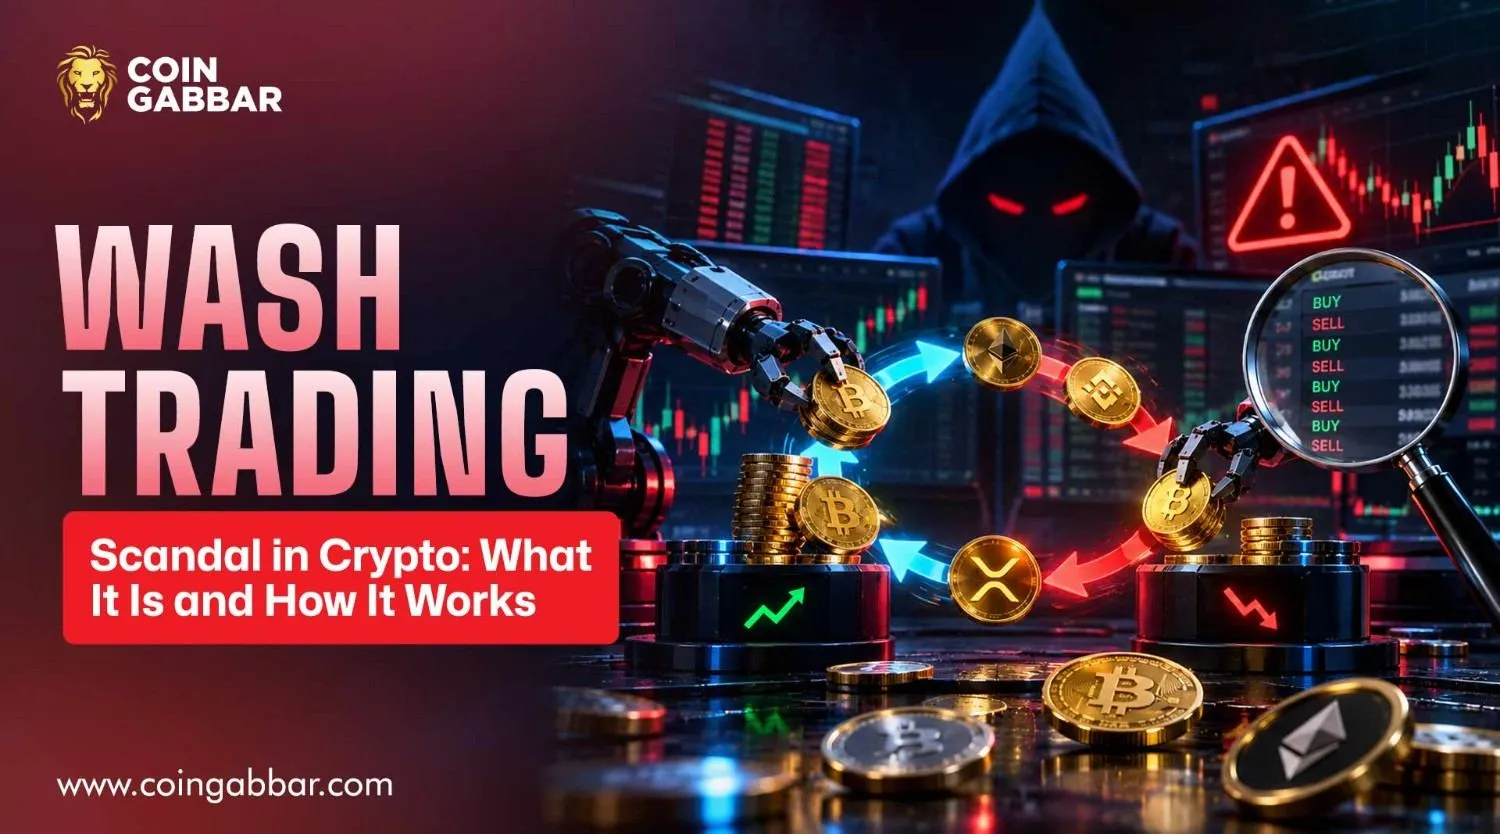
The mechanics behind it are honestly simpler than people expect.
A trader or bot places a buy order and a matching sell order at almost the same price.
The trade settles instantly, with no real risk sitting on either side.
Done repeatedly, this pushes a token's reported volume up fast.
Some exchanges or projects lean on this to climb trending lists or push a trading pair higher in the rankings.
Since volume is one of the very first things new investors check before buying anything, a wash trading scandal can end up shaping decisions that were never actually based on real demand in the first place.
Why This Keeps Happening
Volume works as a trust signal in crypto, whether that trust is deserved or not. A token pulling in heavy daily volume looks safer to trade and easier to exit later, so faking that number becomes tempting for exactly the wrong reasons.
Higher volume can help a token land new exchange listings.
It pushes a project higher on public rankings and trending pages.
It creates a false sense of liquidity, making a thin, illiquid token look easy to trade, a trick that shows up just as often in outright rug pull scams.
It pulls in retail investors who assume all that activity must mean something real.
None of it actually reflects genuine demand. That gap between what the numbers show and what is actually happening underneath is where a wash trading scandal ends up doing the most damage.
Real Cases Regulators Have Already Gone After
This is not just a theoretical risk. Enforcement agencies have pursued this exact behavior more than once, and the cases are public.
The SEC has charged several firms over wash trading schemes tied to crypto assets, including market makers accused of artificially inflating trading activity to make tokens look more active than they were.
The CFTC has run its own cases too, going after firms that arranged offsetting trades carrying essentially zero real market risk, purely to generate misleading volume numbers.
Similar red flags show up in past crypto rug pull scandals, where inflated activity was used to lure investors before funds disappeared entirely.
None of this is rare or isolated. A wash trading scandal tends to surface almost every time a market segment grows quickly, simply because volume becomes the easiest number for someone to fake, something that also shows up often in fast-moving corners of the market like the Solana memecoin scene.
Warning Signs Worth Paying Attention To
A wash trading scandal rarely announces itself outright, but a handful of patterns tend to repeat across cases.
Volume that spikes suddenly with no matching news, listing, or announcement behind it.
A token trading heavily on a single exchange while barely moving anywhere else.
Order books that look unusually thin compared to whatever volume is being reported.
Price staying oddly flat even though trading activity is supposedly through the roof.
No single one of these proves manipulation on its own. But when a few of them show up together, that is usually a good reason to slow down and dig a little deeper before trusting what is on the screen, and it's worth cross-checking against a running list of active crypto scams to see if a pattern has already been flagged elsewhere.
What This Actually Costs Everyday Investors
The damage from a wash trading scandal is rarely obvious right away. It tends to surface later, once the real trading volume drops off and the illusion of liquidity disappears along with it.
Investors can end up buying in at prices that were propped up by fake demand all along.
Exit liquidity can vanish almost instantly once the wash trading stops.
Trust in an exchange or token can collapse fast once a scandal becomes public.
Regulatory scrutiny usually follows, and trading sometimes gets frozen entirely while it plays out.
This is exactly why more careful investors look past headline volume numbers and instead check order book depth, wallet concentration, and trading behavior across multiple platforms before assuming any figure is real.
Staying Cautious Going Forward
At the end of the day, a wash trading scandal comes down to appearance versus substance. Fake volume can be manufactured in a matter of minutes, but real demand simply cannot be faked the same way, not for long anyway.
Anyone looking at a token should treat volume as just one data point among several, not proof of genuine interest by itself. Cross-checking activity across independent trackers, staying alert to sudden unexplained spikes, and treating heavy reliance on a single exchange with some suspicion are all simple habits that go a long way here. Following a few reliable cryptocurrency blogs can also help investors stay ahead of new manipulation tactics as they surface.
Conclusion
At the end of the day, a wash trading scandal comes down to appearance versus substance. Fake volume can be manufactured in a matter of minutes, but real demand simply cannot be faked the same way, not for long anyway.
Enforcement cases from the SEC and CFTC make one thing clear: this is not a rare glitch in the system; it is a recurring tactic that regulators are actively working to shut down.
Every wash trading scandal that comes to light adds one more reminder that headline numbers on an exchange are not automatically trustworthy just because they look impressive.
Disclaimer: This article is written only for general information and educational purposes. It does not offer financial, investment, or legal advice of any kind. Readers should conduct their own research before making any investment decision.