Senate New Crypto Tax Bill: 5 Changes That Could Affect Users Wallet
New Crypto Tax Bill Targets Stablecoin Payments, Gas Fees, Wash Sales
Senate Republicans have introduced a New Crypto Tax Bill called the ADAPT Act, short for Aligning Digital Assets with Principles of Taxation Act. Sen. Steve Daines introduced it on September 30, 2026.
The proposal would write specific federal tax regulations for digital assets. Its key provisions cover stablecoin payments, small network fees, and wash-sale rules. It is only a proposal, not law.
At a Glance
| Key Point | What the Proposes |
| Bill | ADAPT Act |
| Tax relief for qualifying purchases | |
| Network fees | No gain or loss recognized on qualifying fees of $10 or less |
| Wash sales | Crypto regulation extended to digital assets |
| Staking and mining | Specific tax and income-sourcing rules |
| Crypto lending | Laws for certain qualifying loans |
| Status | Introduced, not law |
What Is the ADAPT Act and Why Was It Introduced?
Most U.S. tax regulations were written before blockchain existed. As a result, they do not clearly cover every kind of digital-asset transaction. The ADAPT Act tries to fill those gaps with laws built for crypto. Senate lawmakers are pursuing this tax bill separately from the wider debate over crypto market structure.
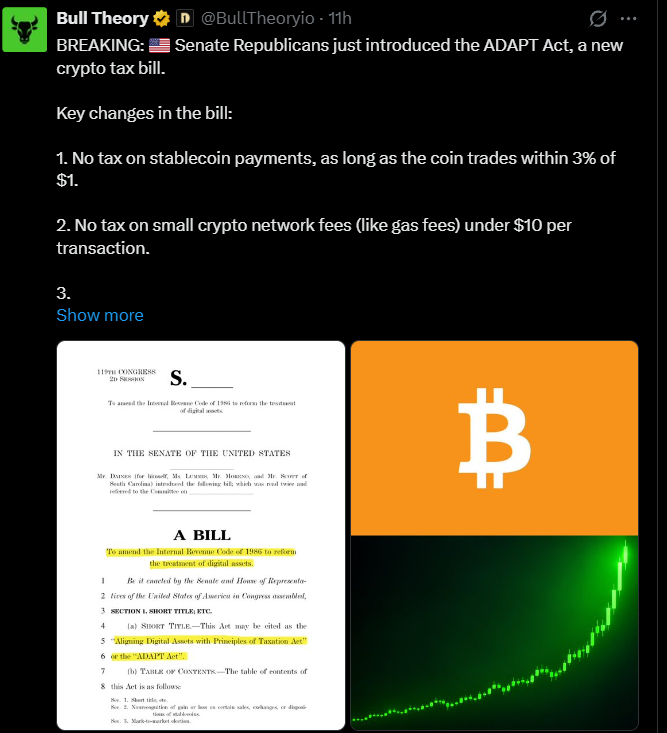
Source: Bull Theory
What Could Change for Crypto Users Under the New Crypto Tax Bill?
Stablecoin Payments Could Get Tax Relief
The bill would give tax relief for qualifying U.S. dollar stablecoin payments. It applies to buying goods and services, and conditions apply. Early reports say the coin would need to trade close to $1, within about 3%.
Crypto Network Fees Under $10
Paying a small gas fee can count as a taxable event today. The acts would stop that for qualifying network or transaction fees of $10 or less. Limits apply to certain traders, dealers and high-volume users.
Crypto Wash-Sale Rules, Staking and Mining
Wash-sale regulations already apply to stocks. They stop investors from claiming a loss when they sell an asset and quickly buy the same one back. The act would extend similar rules to digital assets. This does not simply end tax-loss harvesting. It would limit loss claims in trades that fall under the new crypto regulations. Traders who sell at a loss and rebuy right away would be the ones affected.
The bill also covers staking and mining. It sets out when rewards are taxed and where that income is sourced. A clearer set of laws could help people who earn crypto this way.
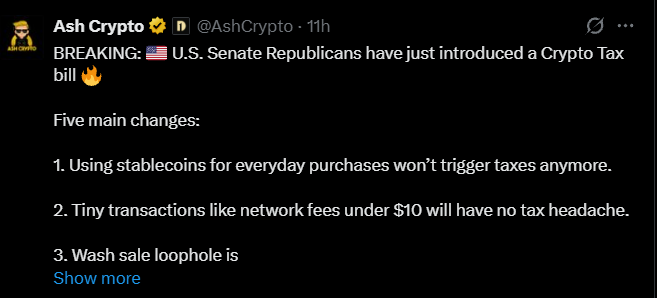
Source: Ash Crypto
Other Crypto Tax Changes in the ADAPT Act
The bill goes beyond the headline items. It would also:
-
Set laws for certain digital-asset lending transactions.
-
Allow mark-to-market accounting for eligible dealers and traders.
-
Change how some foreign investors trading through U.S. brokers are treated.
-
Ease charitable giving rules for widely traded digital assets, with reports saying no formal appraisal would be needed.
-
Define and sort different types of digital assets.
New Crypto Tax Bill Timeline: What Happens Next?
-
September 30, 2026: Sen. Daines introduces the ADAPT Act.
-
Next step: The act must move through the Senate.
-
Congress: Its provisions would need to be reconciled with any related House legislation.
-
President: Both chambers must approve it before it can be signed.
-
Start date: The proposal generally targets tax years after 2026, so changes could begin in 2027. Individual provisions may have different dates.
What It Means for Traders and Investors
Not everyone would feel these changes the same way. Everyday users could see the biggest effect from the stablecoin and fee provisions. Active traders may care most about the wash-sale rules. Stakers and miners would watch the new reward-sourcing rules. Businesses and dealers may be affected by the accounting and lending provisions.
Final tax treatment depends on the law that actually passes. It also depends on each person's situation. Today's rule stay in force until Congress changes them.
Conclusion
The New Crypto Tax Bill is a proposed overhaul of several digital-asset tax regulations. It touches stablecoin spending, small fees, wash sales, staking, mining, and more. Many parts could simplify life for everyday users, while others could tighten rules for traders. Readers should keep proposed rules separate from the laws that apply now. The act has a long road through Congress.
Disclaimer: This article is for informational purposes only and is not tax, legal, or financial advice. Crypto assets are volatile, and tax rules can change. Please speak with a qualified tax professional about your own situation.