Chainlink News: Can CCIP Give DeFi Borrowers More Buying Power?
Chainlink News: Why Security Matters for Borrowing Limits
Chainlink News today: Kamino, a Solana lending protocol, says a security review led it to adopt Chainlink CCIP as its standard for underwriting cross-chain collateral. The announcement is dated October 20.
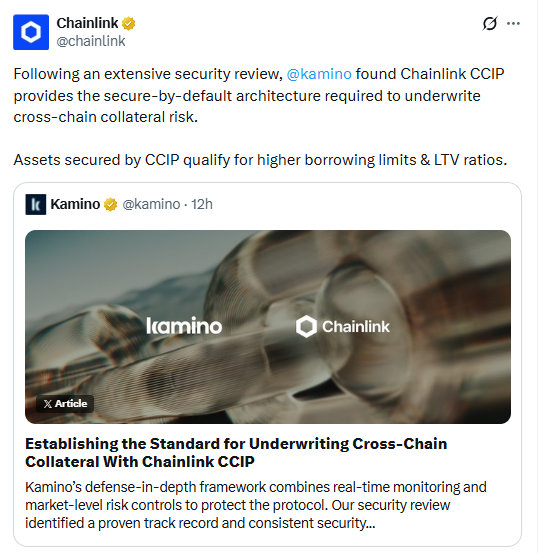
The lending protocol says assets secured through CCIP can qualify for higher borrowing caps and loan-to-value (LTV) ratios. It has not published the affected assets, the size of any increases or the criteria each asset must meet. The announcement therefore describes a potential underwriting advantage, not a blanket increase for every CCIP-connected token.
What Kamino Decided After Its CCIP Review
Term | Meaning |
LTV ratio | Share of collateral value a user can borrow |
Cap | Limit on how much of an asset a market accepts |
CCV | Extra verifier that can be added to CCIP transfers |
Kamino's review reached three points:
Cross-chain tokens are harder to underwrite than single-chain tokens
Default setup: Kamino describes CCIP's default verification setup as a baseline for assessing collateral. It cites 16 independent, security-reviewed node operators. Chainlink's docs describe a default committee with a configured signer set and threshold, and the number was not confirmed in the documentation reviewed. Check the configuration for each deployment
Extra verifiers: Kamino says CCIP 2.0 supports additional Cross-Chain Verifiers. Under the configured policy, these can add another approval requirement to transfers. The exact requirements depend on the verifier configuration
Chainlink confirmed the arrangement on X.
Chainlink News: Why Cross-Chain Security Affects Borrowing
Kamino says a cross-chain token's solvency depends on the weakest mint-and-burn link on any chain it touches. Unbacked supply created elsewhere can flow into every market that accepts the token.
Its answer is to assess the cross-chain configuration itself. Kamino also describes solvency signals wired to circuit breakers, live today for a subset of cross-chain assets:
A gap between a token's DEX price and its peg
A mismatch between supply and verifiable backing
An unexplained jump in supply
Kamino says tokens on bespoke per-lane setups face heavier diligence, lower caps and, in some cases, rejection or delisting. It frames this as what can be measured, not a judgment on issuers.
Kamino's reported use of Chainlink Data Streams for RWA pricing is a separate integration from its stated the cross-chain protocol policy. Pricing infrastructure alone does not establish that a particular asset qualifies for higher borrowing limits.
What Is Confirmed and What Is Not Yet Known
Item | Status |
CCIP adopted as a collateral standard | Stated by Kamino, confirmed by Chainlink |
Higher caps and LTVs for CCIP-secured assets | Stated; no figures disclosed |
Named qualifying assets | Not named in the material reviewed |
Effect of custom verifiers on eligibility | Not stated |
This Chainlink News check found no list of assets, caps or LTV changes. Chainlink's docs say outcomes depend on issuer, pool and verifier choices.
Kamino also claims that CCIP has avoided funds-loss exploits among widely used bridges. This report did not independently verify that comparative claim, which depends on the bridges included, the definition of a funds-loss exploit and the period assessed.
Neither post mentions LINK token demand. No direct effect is established.
The Bottom Line
This Chainlink News review finds a stated policy change, not a published list of boosted assets. Treat higher limits as conditional on each asset's CCIP setup until Kamino publishes figures.
YMYL Disclaimer: This article is for information purposes only and is not financial, investment, or trading advice. Information is based on Kamino's October 20, 2026 post and analysis, Chainlink's confirming post as supplied and Chainlink's CCIP documentation, as of October 21, 2026. Caps, LTVs and eligibility can change at any time. No wrongdoing is alleged or implied. Crypto assets are volatile and carry risk of loss, including full loss of funds. Always verify current details directly with official sources and consult a licensed advisor before making investment decisions.