RBI Crypto Card Rules: Is a Crackdown Coming for Offshore Card Users?
RBI Crypto Card Rules: Is a Crackdown Coming for Offshore Card Users?
As of November 2, 2026, RBI crypto card rules have come under the spotlight after a post on X claimed that the Reserve Bank of India and the Financial Intelligence Unit-India (FIU-IND) are tightening checks on offshore cards used by Indian residents.
The claim comes from that post alone. Neither regulator has made a public statement, so this crypto news today remains unconfirmed.
What Is the Offshore Crypto Card India Story?
Offshore providers issue these cards from outside India. Users top them up with stablecoins, then pay for everyday purchases or take out cash at ATMs in India.
According to the tweet by @pushpendrakum, regulators are looking at possible breaches of payment rules and FEMA. Some users, the post adds, could face questions on money laundering. At this stage, the post is the only source for these claims.
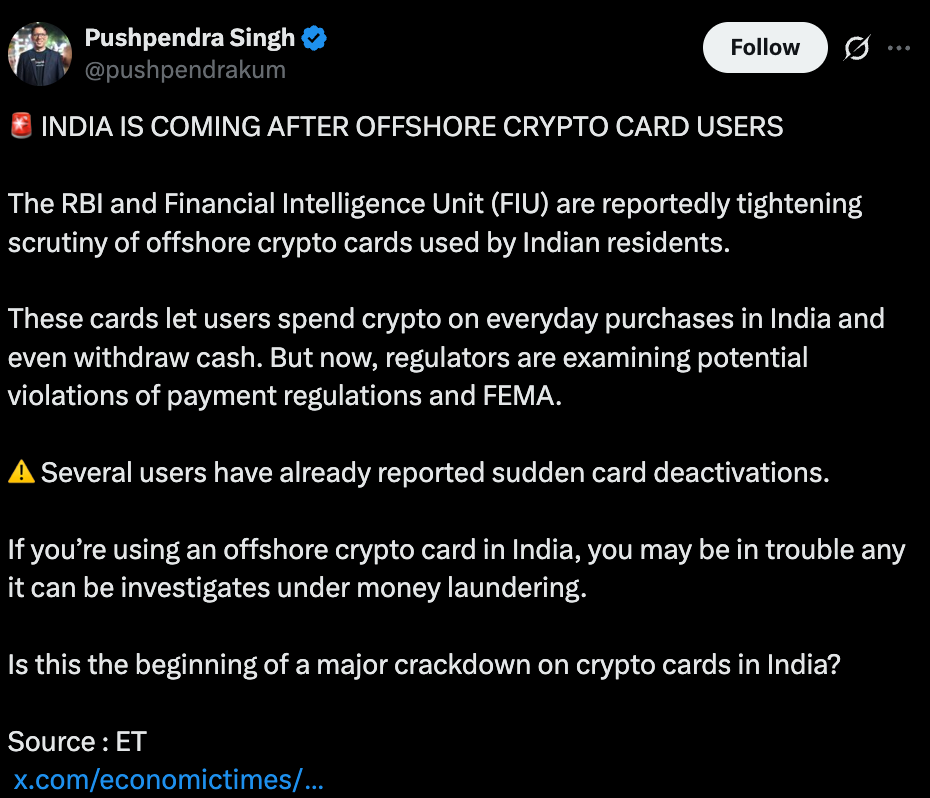
X user @pushpendrakum also covered this news by asking whether it marks the start of a major crackdown.
Crypto Card Deactivated India: What Are Users Reporting?
The tweet says several users saw sudden deactivations. The Economic Times reported on November 2, 2026 that some holders noticed their cards stop working from October 29. No official reason has been given.
This crypto card India news is still thin on confirmed detail, so the table below separates verified points from reports.
Point | Status |
FIU-IND notices to 15 offshore VDA providers (September 9, 2026) | Confirmed |
Scrutiny of offshore cards | Reported only |
Deactivations since October 29 | User-reported |
Public statement from RBI or FIU-IND on cards | None found |
Crypto Debit Card Legal Status: What Do the Rules Say?
The RBI prepaid payment instrument directions say non-bank issuers must obtain RBI authorisation under the Payment and Settlement Systems Act, 2007 before issuing prepaid instruments.
Whether offshore issuers hold that approval has not been addressed publicly, and no new RBI crypto card rules on offshore products were found in the sources checked.
FEMA is India’s main foreign exchange law. A crypto card FEMA violation would depend on how users hold, convert and pay with funds abroad, which is what the tweet says regulators are checking.
Can Residents Spend Digital Assets Under PMLA Rules?
On September 9, 2026, PIB announced that FIU-IND had sent notices to 15 VDA providers under Section 13 of the Prevention of Money Laundering Act.
The rule is straightforward: any virtual digital asset provider serving Indian users, offshore or onshore, has to register. What counts is the activity, not whether the company has an office in India.
Here is what that announcement did and did not cover:
The notices named exchanges, not cards.
FIU-IND also sent takedown notices for their apps and URLs under the IT Act.
The government repeated that digital asset products are unregulated and risky.
FIU-IND is the agency that oversees these reporting entities.
That announcement may become the starting point for FIU crypto card scrutiny, though no FIU RBI crypto card action has been announced so far.
If a crypto card money laundering India probe does begin, KYC and AML norms would probably be checked first, with FEMA compliance coming next
Expert View: What Could RBI Crypto Card Rules Mean?
Analysts following crypto news may read the RBI crypto crackdown talk as an extension of earlier action against unregistered providers.
The same logic could reach cross-border card payments funded by USDT card spending.
If action follows, users could face blocked cards, fresh KYC requests or FEMA queries. Whether stablecoin payments users make through cards will be restricted remains open.
Anyone who wants to use crypto card in may watch for RBI crypto card rules and any RBI authorisation notice, since a formal statement has not arrived.
Disclaimer: This article is for information only and is not financial, legal, or investment advice. Digital assets are volatile. Verify details with official sources before making any decision






