What Is a Liquidation Cascade? $488M Gone After One Fed Speech
How Did $488M Vanish From Crypto in One Session?
Nearly $488 million in leveraged crypto positions was wiped out within 24 hours on August 28, 2026. Fed Chair Kevin Warsh spoke at Jackson Hole that day. Tracking data showed $487.68 million in forced closures across 97,691 traders. Bitcoin fell from about $80,000 to a low of $76,909.
A liquidation cascade is a chain of forced position closures, where each closure pushes the price further and triggers the next one. This article explains how the August 28 selloff worked, what the data shows, and how traders try to limit the damage.
Why Were $488 Million in Crypto Positions Liquidated?
On August 28, 2026, about $487.68 million in crypto positions was reportedly liquidated within 24 hours, according to CoinGlass data. The selloff followed a hawkish Jackson Hole speech by Fed Chair Kevin Warsh.
Higher interest-rate expectations put pressure on Bitcoin, and forced closures hit leveraged traders. Long positions made up most of the losses.
How Much Crypto Was Liquidated on August 28, 2026?
The table below lists the main figures reported for the 24-hour window.
Metric | Reported figure |
Total liquidations | $487.68 million |
Traders affected | 97,691 |
Long liquidations | More than $360 million |
Bitcoin liquidations | About $141 million |
First-hour liquidations | More than $200 million |
Largest single liquidation | $11.66 million (ETH-USDT on Binance) |
Long positions made up roughly three-quarters of the total. That split shows how many traders were betting on crypto market higher prices after a strong August rally.
What Is a Liquidation Cascade in Crypto?
An exchange closes a leveraged trade automatically when the trader’s margin can no longer cover the loss. Margin is the collateral a trader posts to keep a position open. Each forced closure adds selling or buying pressure, and that pressure can push other positions past their limits.
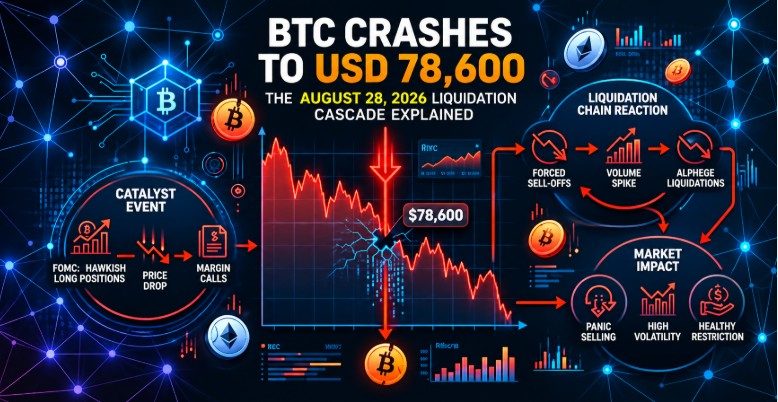
One liquidation is routine, since the order book absorbs it. A market-wide cascade is different. Thousands of positions sit near the same price levels, so they fail together.
Leverage is the reason this happens. It means holding a position larger than the trader’s own funds. Open interest, the total value of open derivatives contracts, shows how large this exposure is. Open interest counts outstanding contracts, so it does not always mean borrowed money, but high open interest with high leverage raises the risk of forced selling.
Key Features of a Forced Selloff
Speed: The first hour alone saw more than $200 million in closures.
Automation: Exchange systems close the positions, so no trader can negotiate.
Feedback loops: Each closure moves the price, and the new price creates the next closure.
One-sided damage: Long traders took most of the loss on August 28.
How Does Leverage Lead to Forced Liquidation?
A common rule says a 10x position is wiped out by a 10% move against it. This is only a rough guide. A 10% adverse move equals about 100% of the initial margin, but exchanges close positions earlier than that.
Exchanges set a maintenance margin, which is the minimum collateral a position must keep. Once equity falls to that level, the liquidation engine starts closing the trade. Fees and funding payments can bring that point even closer.
Two more terms help explain the process:
Liquidation price: The price at which the exchange begins to close the position.
Bankruptcy price: The price at which the trader’s margin reaches zero. The liquidation price sits before it, which leaves a small buffer to cover closing costs.
Forced closures usually run as market orders. In a fast market, the fill price can be worse than expected, which is called slippage. This adds more pressure on the price.
Cross Margin vs. Isolated Margin
Margin mode decides how much of a trader’s account is at risk.
Isolated margin: Only the collateral assigned to one position is at risk. The loss is capped at that amount.
Cross margin: The whole account balance backs all open positions. This pushes the liquidation price further away, but a bad move can drain the entire balance.
Adding extra collateral can delay liquidation, but it also raises the amount that can be lost.
How Did the Fed Speech Connect to the Liquidations?
Markets had climbed before the speech. Bitcoin rose to around $81,000, and many traders held long positions. The Federal Reserve confirmed that Warsh spoke at Jackson Hole on August 28, and Reuters reported a hawkish reaction in markets.
Traders reacted quickly. The odds of a September rate hike rose to about 60% from roughly 35%. Short-term Treasury yields rose, and the dollar got stronger. Higher expected rates usually reduce demand for risky assets such as Bitcoin.
The timing points to a link, but timing alone does not prove the speech was the only cause. Crowded long positions and high leverage had already made the market fragile. The speech acted as the trigger, and the leverage made the move larger.
Bitcoin vs. Ethereum: Where Did the Pressure Fall?
Bitcoin positions accounted for about $141 million of the total. Ethereum also saw heavy closures, including the largest single liquidation of the day, an $11.66 million ETH-USDT position on Binance.
Both coins hold the biggest pools of open interest, so their forced closures are the largest in dollar terms.
Altcoins have thinner order books. Smaller orders can move their prices further, so losses often run deeper in percentage terms.
How Does a Liquidation Cascade Work Step by Step?
Traders open leveraged positions, mostly long ones after a rally.
Unexpected news arrives and prices move fast.
Some positions come close to their liquidation price.
Exchanges close positions that no longer meet the maintenance margin.
Forced selling adds pressure and pushes prices lower.
More positions cross their liquidation price, and the cycle repeats.
Decentralized lending platforms work in a similar way, but they use a health factor instead. This number measures how safe a loan is. When it falls below 1, the protocol can sell the collateral to repay the debt. On centralized exchanges, the exchange’s own engine does the closing.
Why Do Macro Events Move Crypto So Fast?
Crypto trades 24 hours a day, so macro news reaches the market right away. Interest rates set the cost of borrowing and the appetite for risk. Sticky inflation keeps rate cuts far away, and a stronger dollar tends to weigh on Bitcoin.
Leveraged traders cannot wait for a recovery because margin calls arrive before prices bounce back. Early reports showed Bitcoin recovering slightly to about $77,700, but cascades do not always reverse fast.
How Can Traders Reduce Liquidation Risk?
Use lower leverage: Lower multiples leave more room before the liquidation price.
Keep a margin buffer: Extra collateral moves the liquidation price away, though it also increases the amount at risk.
Know the stop-loss limits: A stop order is not guaranteed to fill at the chosen price, especially in a fast market.
Watch open interest and funding rates: High open interest with extreme funding often signals crowded positions.
Use a liquidation heatmap: It shows price zones where many positions may close.
Follow central bank events: Speeches and data releases can move prices within minutes.
Risk only affordable capital: Money needed for rent or bills should not sit in leveraged trades.
None of these steps removes crypto trading risk completely.
Liquidation Cascade vs. Short Squeeze: What Is the Difference?
A cascade usually starts with falling prices, and long positions are closed by force. A short squeeze runs the other way. Prices rise, short sellers face losses, and their forced buying lifts prices higher. The difference lies in direction and in who gets hurt. On August 28, long traders took the loss.
Can Another $488M Cascade Happen?
Another event of this size can happen. Macro news, crowded leverage, and thin liquidity form the same recipe each time. Heatmaps and open interest show where stress is building, not when it will break. Careful leverage management is the stronger protection, because traders with room to spare can survive swings that wipe out others.
Disclaimer
This article is for informational purposes only and is not financial advice. Crypto trading, especially with leverage, carries high risk and can lead to total loss of capital. Readers should research independently and consult a licensed advisor before making decisions.
















