What 4.2M UK Crypto Holders Reveal About Adoption's Next Phase
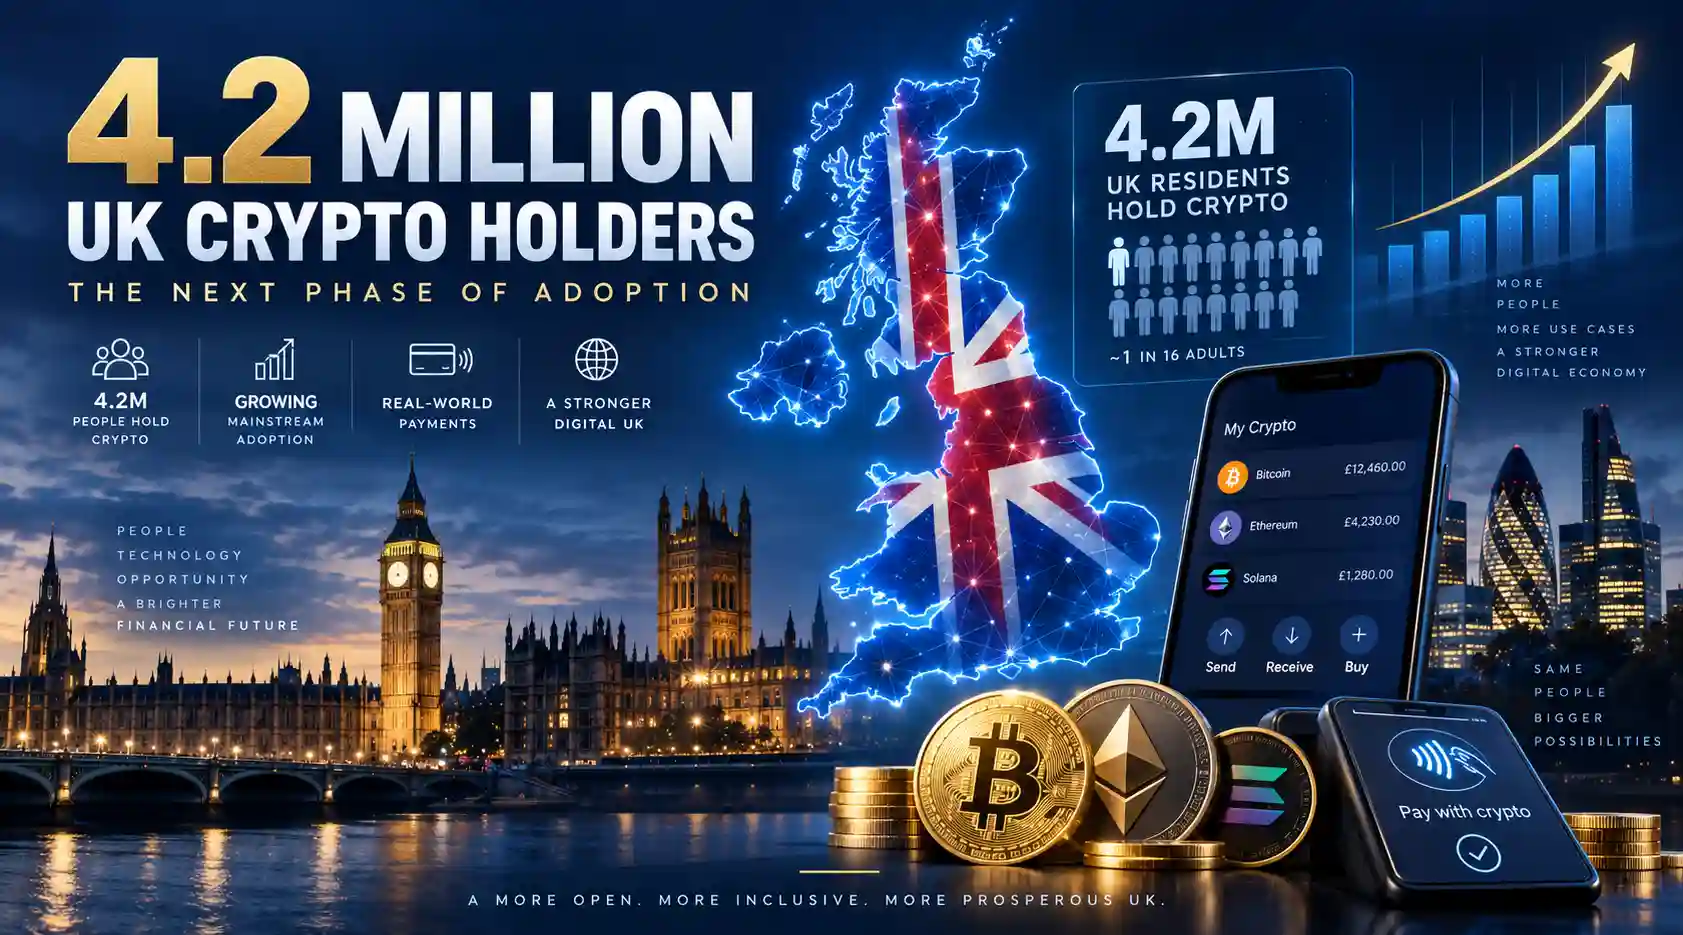
Crypto ownership in the United Kingdom has quietly stopped being a fringe activity. Figures published by the Financial Conduct Authority put the number of UK adults holding cryptoassets at roughly 4.2 million, or about 12 per cent of the adult population. That is close to double the share recorded four years earlier. For a market that is often described in terms of speculative cycles, the more interesting story is the one underneath the price charts: a large, and now fairly ordinary, group of retail holders who bought through a mainstream venue and have kept holding.
At The Investors Centre we research this market by opening and funding real accounts with our own money, then publishing what actually gets charged rather than what a rate card claims. Applied to the UK crypto market, that approach surfaces three patterns worth setting out, because they say something about where adoption goes next.
1. The cost of access is now the deciding factor, not availability
Five years ago the practical question for a UK buyer was whether they could get access at all. Banking relationships were fragile, onboarding was slow, and sterling deposit routes were limited. That problem has largely been solved. Faster Payments deposits are widely supported, verification is usually same day, and the major venues compete for UK customers directly.
What replaced it is a cost question, and it is a harder one to see. The advertised trading fee is rarely the whole cost. Spread, the conversion charge applied when sterling is routed through another currency, the withdrawal fee on the way out, and in some cases a separate network fee all sit alongside it. Two venues quoting a similar headline percentage can produce materially different outcomes on the same order. Our comparison of the leading UK crypto exchanges works through those layers on funded accounts rather than from published documentation, which is the only way to see the total figure a holder actually pays.
2. Regulation has reshaped how the market is marketed, not how it is used
The FCA's financial promotions regime, in force since October 2023, changed what UK consumers see before they buy. Risk warnings are mandatory, a cooling off period applies to first time customers of a firm, and incentives such as refer a friend bonuses were removed. Several international venues withdrew from the UK retail market rather than comply.
The behavioural effect has been narrower than some expected. Survey work accompanying the FCA's own research suggests that holders have not exited in large numbers, but the route in has consolidated around a smaller group of registered firms. For anyone studying the market, that consolidation matters more than the headline adoption number. A market where 4.2 million people hold through a dozen venues behaves differently from one where they hold through fifty.
3. Holding periods are lengthening
The stereotype of the UK crypto buyer as a short term speculator is increasingly out of date. The FCA's consumer research indicates that a majority of holders describe their position as a long term one, and a significant proportion have held for more than three years. That changes which product features matter. Custody arrangements, the treatment of assets in insolvency, staking terms and the quality of transaction records for tax reporting all become more important than the fee on a single trade.
It also creates an information gap. Most published comparison material is written for the moment of purchase. Very little of it addresses what a five year holder needs to know, which is how an exchange behaves during the long quiet stretches between buying and selling.
What this means for the next phase
If UK adoption continues at its current pace, the marginal new holder will look less like an early adopter and more like a mainstream saver who already uses an investment platform for equities and funds. That person will compare a crypto venue against the platforms they already hold, and they will apply the same tests: total cost, clarity of reporting, the strength of the regulatory perimeter, and how straightforward it is to get money out.
Those are unglamorous criteria. They are also the ones most likely to determine which venues hold UK market share in three years' time. The research agenda that follows from them is practical rather than predictive. Fund an account, run the transactions, record what was charged, and publish it.
Nothing here is a recommendation to buy or sell any asset. Cryptoassets are unregulated in the UK for most consumer protection purposes, are highly volatile, and holders should be prepared to lose the full amount invested. The purpose of the work is narrower and, we think, more useful: to establish what UK holders are actually paying and receiving. Our full methodology and the underlying research are published at The Investors Centre.
Disclaimer: This article is provided for informational and educational purposes only and does not constitute financial, investment, legal, or tax advice. Crypto assets are highly volatile and may involve significant risk, including the potential loss of the full amount invested. Readers should conduct their own research and consider their individual circumstances before making any financial decisions. Regulatory protections may vary depending on the crypto asset, service, and jurisdiction
Also read: